The sale price is not automatically the money an owner keeps. A proposed exit can involve approvals, outstanding debt, lease issues, professional fees and requirements imposed on the buyer or seller.
Identify the transfer pathway
Review who must approve a buyer and which documents govern the transfer. Ask whether the buyer enters a new agreement and whether training or refurbishment is required. Distinguish a sale of business assets from a sale of company shares with appropriate professional advice.
Build a net-proceeds schedule
Start with the proposed consideration and separately list verified deductions, unsettled liabilities and retained cash. Avoid calling the result a valuation. The schedule should explain cash movement if an agreed transaction completes, not predict what a purchaser will pay.
Close out continuing obligations
Track guarantees, supplier accounts, digital access, customer records and post-exit restrictions. Ask who issues each release or consent and when. A completed sale contract does not by itself establish that every third-party commitment has ended.
A worked research example
Illustrative example: an agreed price of 180,000 less 55,000 debt settlement, 8,000 transaction costs and 12,000 required works leaves 105,000 before any other adjustments or tax. Verify every deduction and its timing rather than relying on this simplified arithmetic.
Evidence to gather
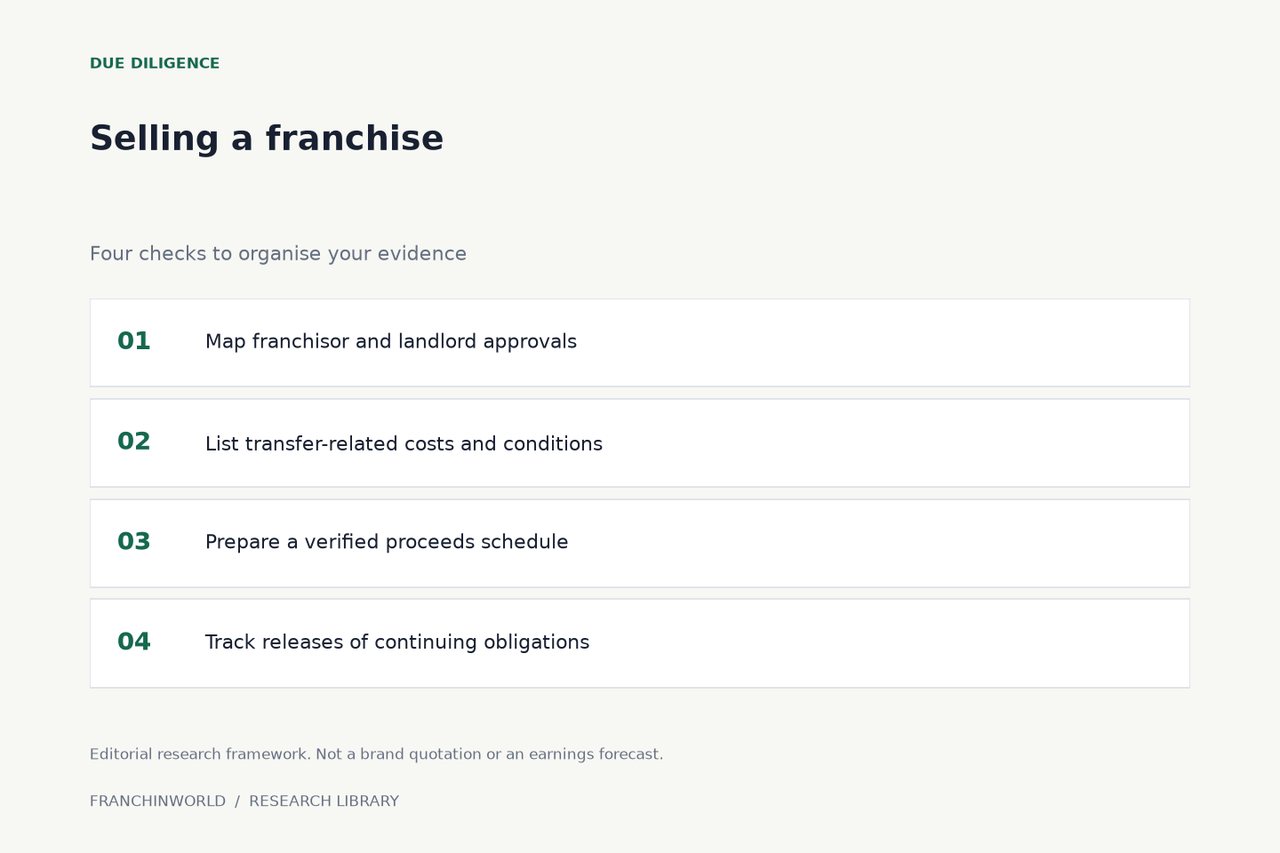
- Map franchisor and landlord approvals
- List transfer-related costs and conditions
- Prepare a verified proceeds schedule
- Track releases of continuing obligations
Before you move forward
Frequently asked questions
Is the advertised asking price net proceeds?
No. Liabilities, transaction costs and other adjustments can change what remains.
Can a buyer take over my existing agreement?
Confirm the actual transfer procedure and whether a replacement agreement is required.
Can this guide estimate my business value?
No. Valuation requires evidence and advice specific to the business and transaction.
Sources and scope
References checked 6 November 2026. The questions, examples and diagrams are our editorial research tools; they are not statements that every franchise has the same terms.
- BFA — Navigating franchise resales: tips for buyers
UK resale due-diligence background; our examples are not valuations.
- SBA — Manage your business
General operating and finance background; local and contractual requirements still need checking.
General editorial information, not personalised legal, tax or financial advice. Confirm local requirements and the actual documents with appropriate advisers. Examples are hypothetical. Contact the editor or suggest a correction.
Continue your research