A cost is easy to miss when it belongs to a different contract, starts after opening or is described as optional without explaining the alternative. A payment register makes those gaps visible without inventing a universal list of charges.
Trace payments beyond the franchisor
Map the landlord, equipment supplier, software provider, insurer and advisers alongside the franchisor. Record who invoices each amount and whether it is one-off, recurring or conditional. An amount absent from the brand’s fee schedule may still be part of operating the proposed business.
Distinguish unknown from zero
Use separate labels for included, quoted, estimated, not applicable and unresolved. Check installation, travel, replacement equipment, local promotion and end-of-contract obligations. These are investigation categories, not a claim that every franchise charges all of them.
Put costs on a calendar
Record the earliest due date and the trigger for payment. A cost payable before finance is released creates a different cash problem from the same amount payable after trading starts. Reconcile the register with agreements and supplier quotations before treating the budget as complete.
A worked research example
Illustrative example: a monthly system charge of 180 is modest beside a fit-out bill, but over 60 months it totals 10,800 before any price changes. Ask whether setup, replacement hardware or transaction charges sit outside that subscription.
Evidence to gather
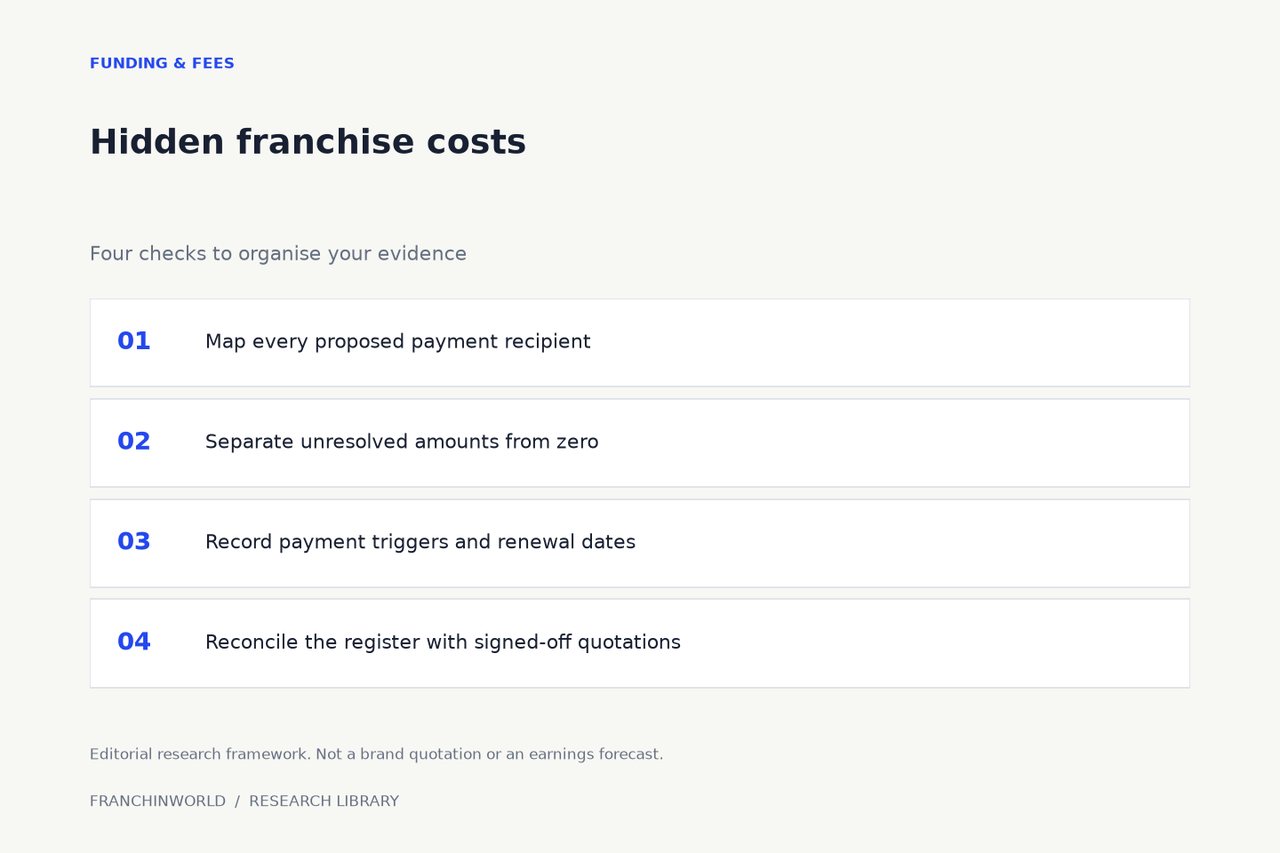
- Map every proposed payment recipient
- Separate unresolved amounts from zero
- Record payment triggers and renewal dates
- Reconcile the register with signed-off quotations
The worksheet below uses editable example inputs. It does not automatically reproduce the scenario or every calculation rule discussed above.
What will it take to open?
Frequently asked questions
Does hidden mean deliberately concealed?
Not necessarily. Costs can be missed because several suppliers and documents are involved.
Should I add a standard contingency percentage?
A contingency is a planning choice, not a substitute for investigating specific missing costs.
Can the register replace contract review?
No. It organises questions and payment timing; it does not determine the meaning or enforceability of terms.
Sources and scope
References checked 6 November 2026. The questions, examples and diagrams are our editorial research tools; they are not statements that every franchise has the same terms.
- SBA — Plan your business
General US business-planning reference, not franchise-specific costs or a forecast.
- SBA — Manage your business
General operating and finance background; local and contractual requirements still need checking.
General editorial information, not personalised legal, tax or financial advice. Confirm local requirements and the actual documents with appropriate advisers. Examples are hypothetical. Contact the editor or suggest a correction.
Continue your research