A machine’s purchase price does not show the business’s dependence on it. Identify which failures stop trading, reduce capacity or compromise service, then check the actual support and replacement arrangements.
Rank equipment by operating dependence
Map each critical function to its equipment and any feasible approved alternative. Include software, connectivity and payment systems where they are essential. A spare appliance is not useful if it cannot perform the required process or fit the premises safely.
Check the service agreement
Identify support hours, fault reporting, response commitments and what parts or labour are excluded. Distinguish an engineer response from a guaranteed repair. Keep warranty, maintenance and finance obligations separate; a financed asset can still require payments during a breakdown.
Build a communication and cash scenario
Assign who contacts the supplier, informs customers and decides whether restricted service is appropriate. Model interrupted receipts and costs that continue. Review insurance terms with a qualified provider rather than assuming every interruption is covered.
A worked research example
Illustrative example: a two-day outage removes an assumed 1,000 of daily receipts while rent and finance payments continue. That is not automatically a 2,000 profit loss; variable costs and customer recovery also need consideration.
Evidence to gather
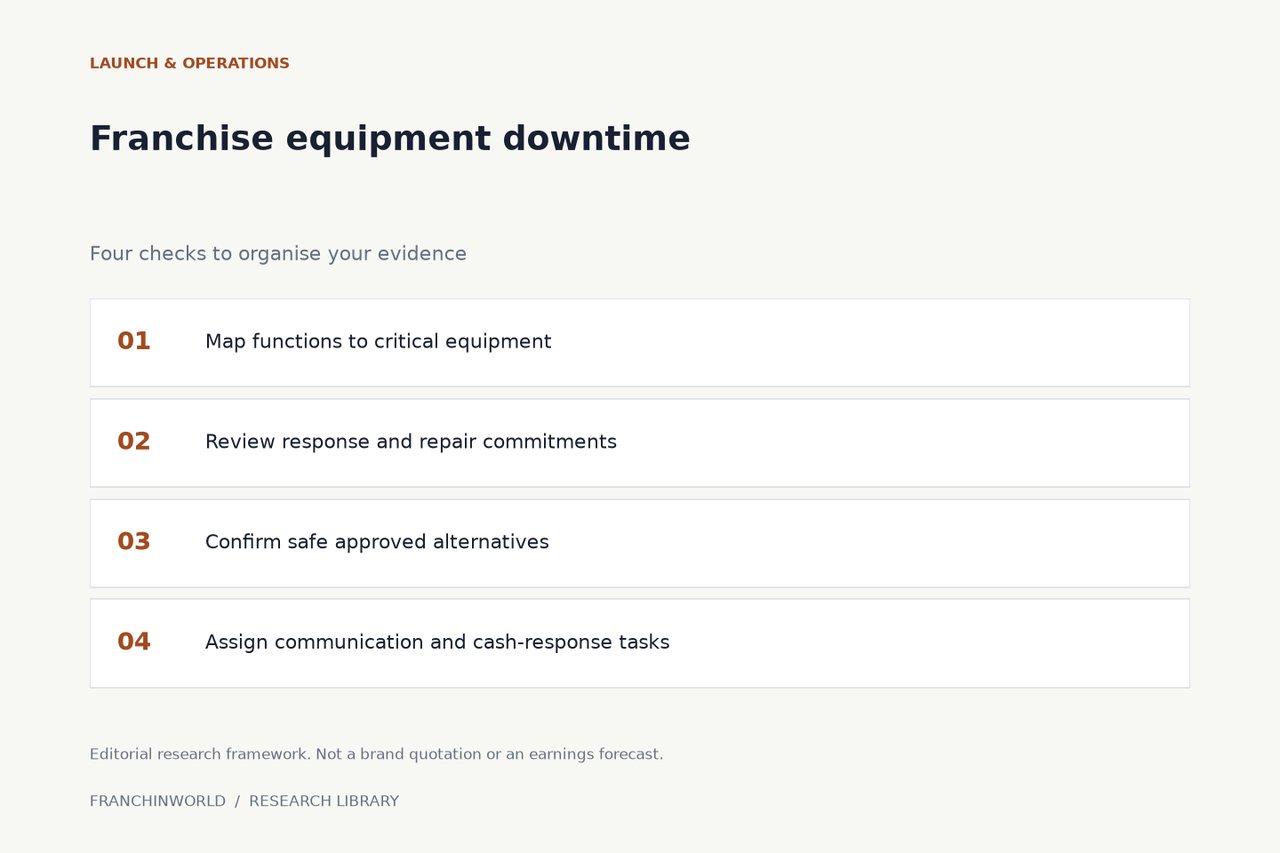
- Map functions to critical equipment
- Review response and repair commitments
- Confirm safe approved alternatives
- Assign communication and cash-response tasks
The worksheet below uses editable example inputs. It does not automatically reproduce the scenario or every calculation rule discussed above.
How long will your cash last?
Frequently asked questions
Does a warranty guarantee uninterrupted trading?
No. Read the remedy, exclusions and timing in the actual terms.
Can I stop finance payments if equipment fails?
Do not assume so. Review the finance and supplier agreements with appropriate advice.
Is lost revenue the same as lost profit?
No. Separate receipts, avoided costs, continuing commitments and recovery effects.
Sources and scope
References checked 6 November 2026. The questions, examples and diagrams are our editorial research tools; they are not statements that every franchise has the same terms.
- SBA — Manage your business
General operating and finance background; local and contractual requirements still need checking.
- British Business Bank — Leasing and hire purchase
UK asset-finance background; actual ownership and payment terms depend on the agreement.
General editorial information, not personalised legal, tax or financial advice. Confirm local requirements and the actual documents with appropriate advisers. Examples are hypothetical. Contact the editor or suggest a correction.
Continue your research