A first outlet that depends heavily on the owner may not be ready to support a second. Expansion changes supervision and cash commitments, even when the brand and operating process are familiar.
Test the first unit without the owner
Identify tasks that currently rely on personal relationships or unrecorded knowledge. Develop management cover and review how performance is monitored. A strong month of sales does not establish that the operation can run reliably while the owner opens another site.
Separate unit and shared costs
Build a budget for the second project and a separate schedule for management, administration and any shared resources. Avoid counting the same reserve in both units. Check whether extracting funds from the first outlet leaves it able to meet its own commitments.
Review approvals and opening obligations
Confirm the offered rights, location approval and any development timetable. Do not assume a successful first franchise grants a right to another territory. Model delays in the new unit while preserving support for the existing operation.
A worked research example
Illustrative example: an owner plans to transfer 30,000 from the first outlet, but 20,000 is already committed to maintenance and tax payments. Only the uncommitted amount can be considered before testing the first unit’s future cash needs.
Evidence to gather
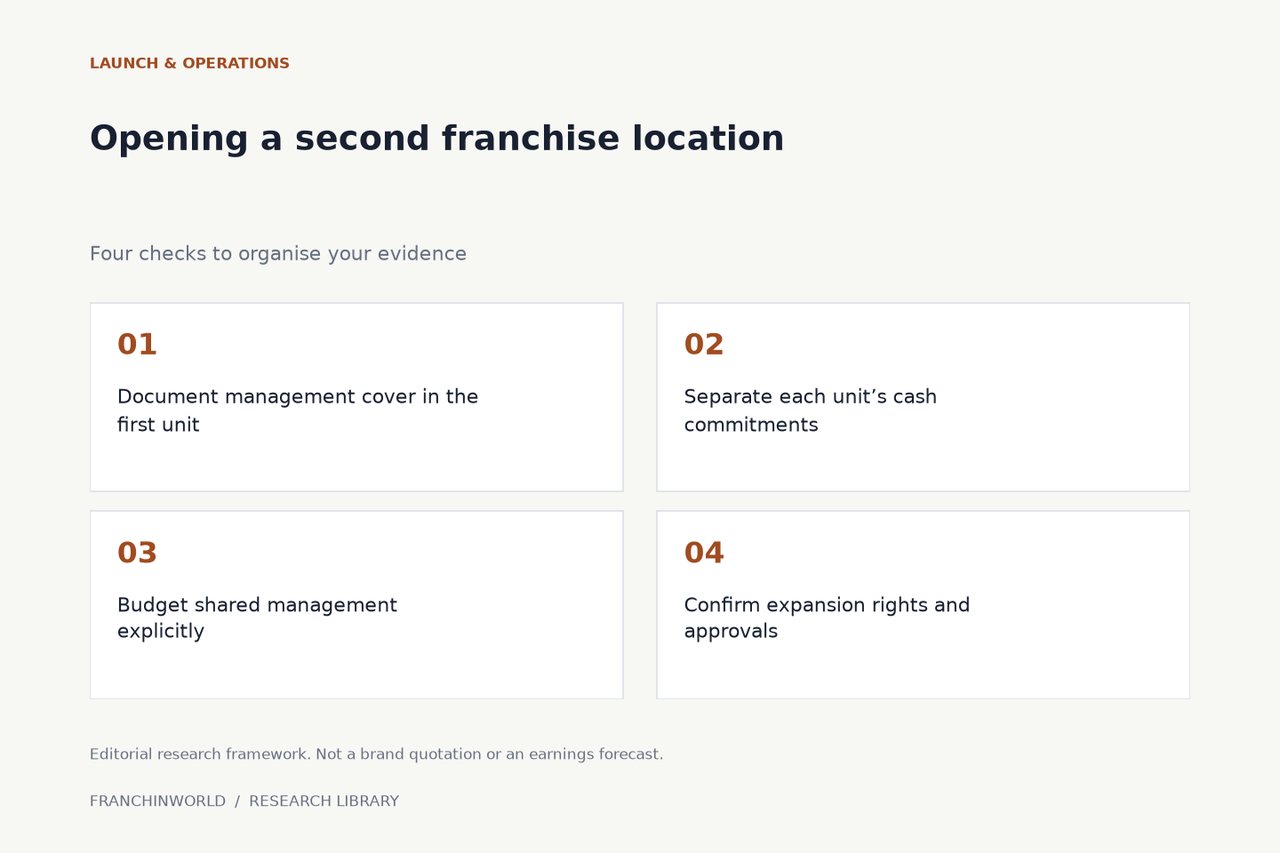
- Document management cover in the first unit
- Separate each unit’s cash commitments
- Budget shared management explicitly
- Confirm expansion rights and approvals
The worksheet below uses editable example inputs. It does not automatically reproduce the scenario or every calculation rule discussed above.
How long will your cash last?
Frequently asked questions
Does one successful location prove a second will work?
No. Site demand, management capacity and funding require fresh assessment.
Can I use the first unit’s full bank balance?
Identify commitments and future operating needs before treating cash as available.
Is multi-unit ownership always allowed?
Confirm the current offer and agreement rather than assuming expansion rights.
Sources and scope
References checked 6 November 2026. The questions, examples and diagrams are our editorial research tools; they are not statements that every franchise has the same terms.
- International Franchise Association — Types of franchise investments
General relationship-model background; not the terms of a specific offer.
- SBA — Manage your business
General operating and finance background; local and contractual requirements still need checking.
General editorial information, not personalised legal, tax or financial advice. Confirm local requirements and the actual documents with appropriate advisers. Examples are hypothetical. Contact the editor or suggest a correction.
Continue your research